On 15 September 2026, Eng. John Kipchumba Tanui, CBS, Kenya's Principal Secretary for ICT and the Digital Economy, published a long essay on LinkedIn with an ambitious title: Positioning Kenya as Africa's Preferred Data-Centre and Compute Hub. It is the most complete public statement yet of how Kenya's government sees this industry. It tells the story of how the country got here, sizes up the competition, admits the risks, and sets out what the state should do next.
Pieces like this usually stay buried in policy language, so we read every word, checked the load-bearing claims against our verified directory, and translated it into plain English.
The one-sentence version
Kenya built the cables. Now it needs the compute. Tanui's opening argument is that every digital transaction, from an M-PESA payment to an AI chatbot answer, has a physical home: a building full of servers, storage and network equipment.
Countries that host those buildings gain speed, control over their own data, technology investment and the base required for artificial intelligence. Countries that do not host them stay dependent. His framing is worth quoting exactly, because it is the whole essay in two lines: "Kenya has already built the cables. The next national assignment is to build the compute."
For a newcomer, the word compute is the one to unpack. Cables are the roads that carry data in and out of the country. Compute is the factory work at the end of the road: the machines that actually process your mobile money record, your eCitizen application or a Kiswahili AI model's training data.
Today, far too much of that factory work for African data happens outside Africa. The PS's sharpest line makes the stakes plain: if African data continues to be processed mainly outside the continent, Africa will "export the raw material of its digital economy and import the resulting intelligence, platforms and services."
The numbers he builds the case on
The essay leans on a handful of figures, mostly from industry and energy bodies. Here they are, with their sources, so you can quote them responsibly.
- Africa has about 18 percent of the world's people but under 1 percent of global data centre capacity. This is the essay's central injustice, and it is consistent with the capacity estimates used widely across industry research.
- The global colocation and interconnection market was worth about US$119 billion in 2025 and is projected to approach US$147 billion in 2026 (PS essay, 15 Sep 2026). That is the pool of investment Kenya is competing for.
- Global data centre electricity consumption could more than double to about 945 terawatt-hours by 2030 (International Energy Agency, Energy and AI, April 2025). Slightly more than Japan uses in a year.
- Ireland's data centres grew from 5 percent of national electricity in 2015 to 22 percent in 2024 (PS essay, citing Irish statistics). This is presented as a warning, not a trophy.
- A large data centre may engage more than a thousand people at peak construction but keep only about 50 permanent workers (PS essay, citing Northern Virginia, the world's largest market). Jobs, in other words, are not the main prize.
One habit worth copying from the essay: it consistently separates operating capacity from pipeline. Announced projects and operating megawatts are treated as different things, which is exactly the discipline our own directory applies to every facility we track.
How Kenya got here: the four phases
Tanui tells Kenya's data centre history in four stages, and the arc explains why the current moment feels different.
- Private halls. Government agencies, universities, banks and large companies built their own server rooms for records and internal systems. Banking digitisation, from ATMs to mobile banking, made financial institutions the first serious demand base.
- The telecoms era. Operators built facilities for voice, internet and mobile money. Safaricom began offering cloud services around 2010, and those investments carried M-PESA, proving a globally significant platform could run on infrastructure hosted in Kenya.
- Commercial specialised hosting. The East Africa Data Centre opened in Nairobi in 2013 under Liquid Intelligent Technologies and Africa Data Centres, marking the shift to purpose-built commercial facilities. Then iColo's carrier-neutral Nairobi One launched in 2019, letting many networks, banks and content providers interconnect under one roof without being tied to a single operator. That model turned Nairobi from a national telecoms centre into a regional interconnection market.
- The current stage. International operators, public cloud infrastructure and facilities designed for dense cloud and AI workloads. This is the phase the essay is really about, and the one where the "preferred hub" question will be decided.
We track the whole market this history produced in our Kenya data centre market outlook for 2025 to 2030 and in our verified facility directory.
What is actually real today (and what is still promised)
This is where the essay earns its credibility, because it is more sceptical than most government writing. Here is the state of play it describes, cross-checked against what we track.
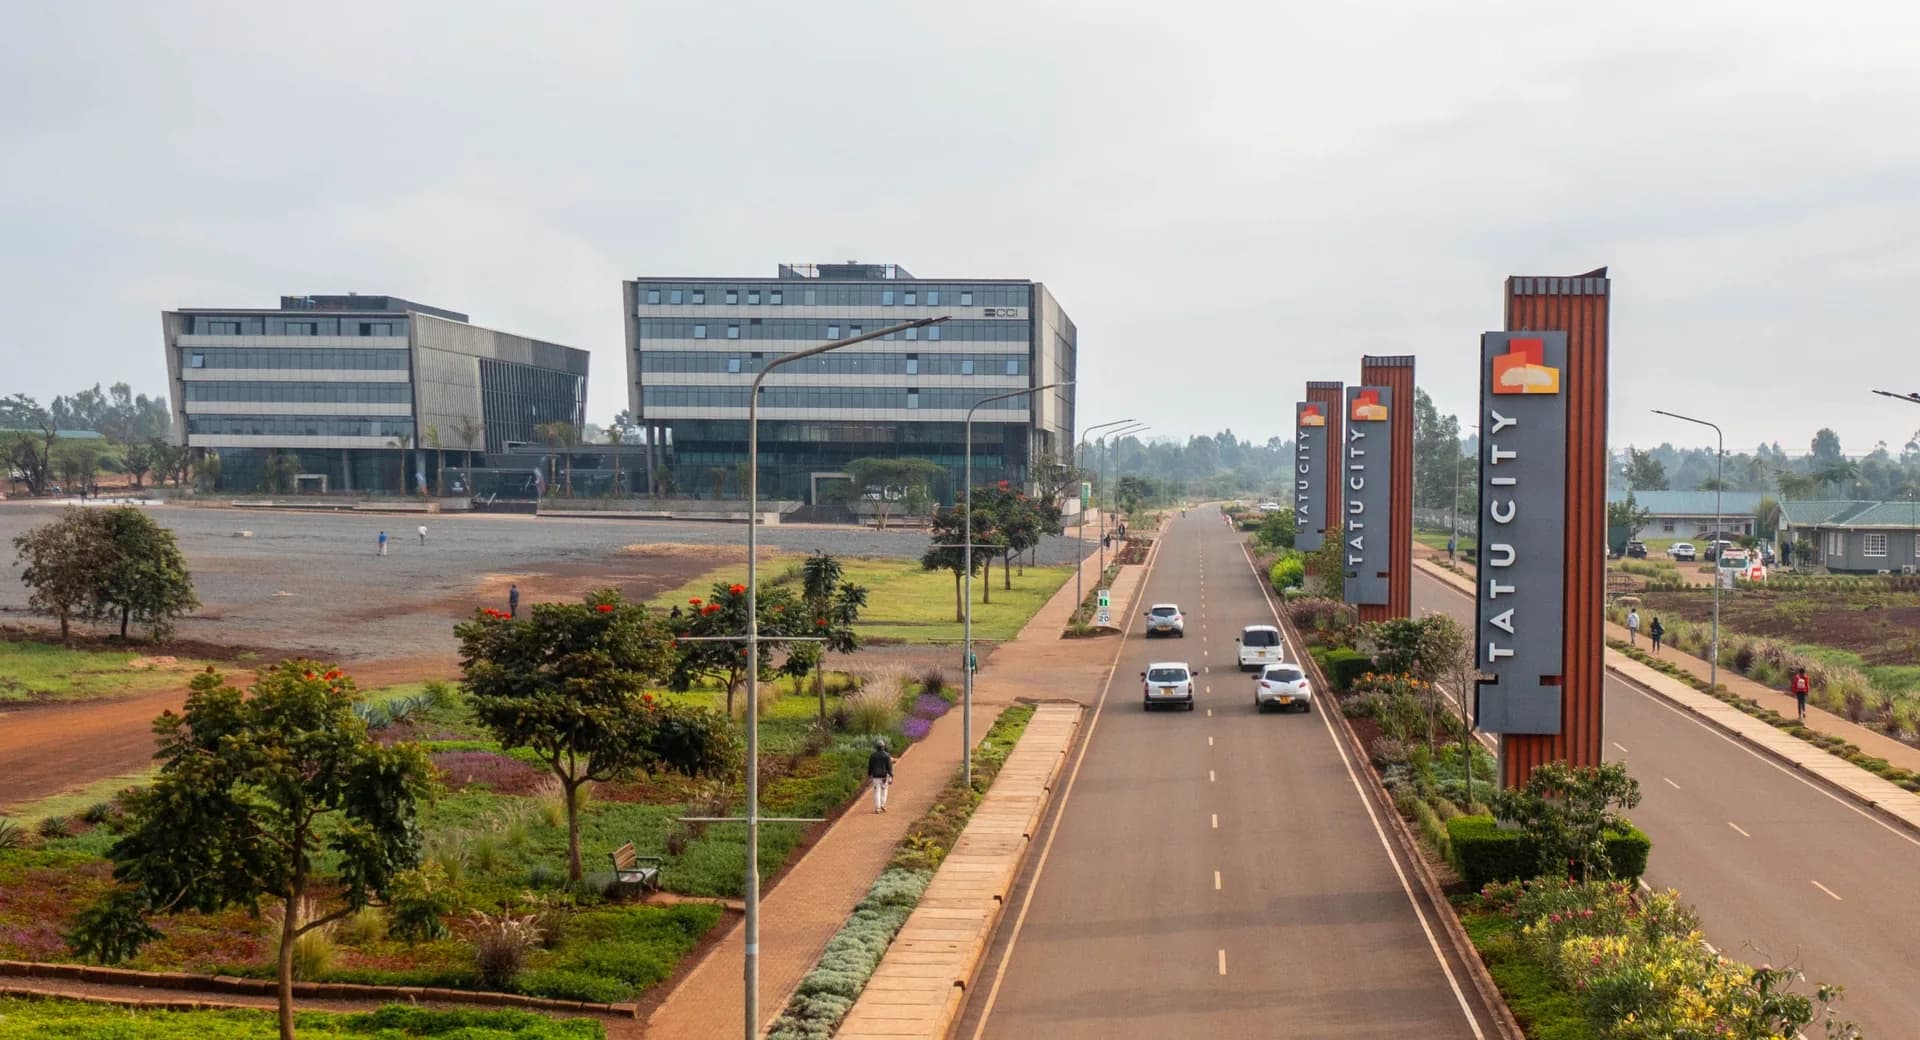
The Oracle cloud region: announced, not live. President Ruto announced Kenya's first Oracle Cloud Infrastructure (OCI) public cloud region in January 2024. In January 2026, iXAfrica was named as the host partner in Nairobi (iXAfrica announcement, 27 Jan 2026). The region is under development and comes into service only after construction, power and cloud fit-out are done.
When it lands, it will be the first real test of whether Kenya can host a global public cloud region, not just interconnection. You can see the facility it will run on, iXAfrica NBOX1 in our verified facility directory.
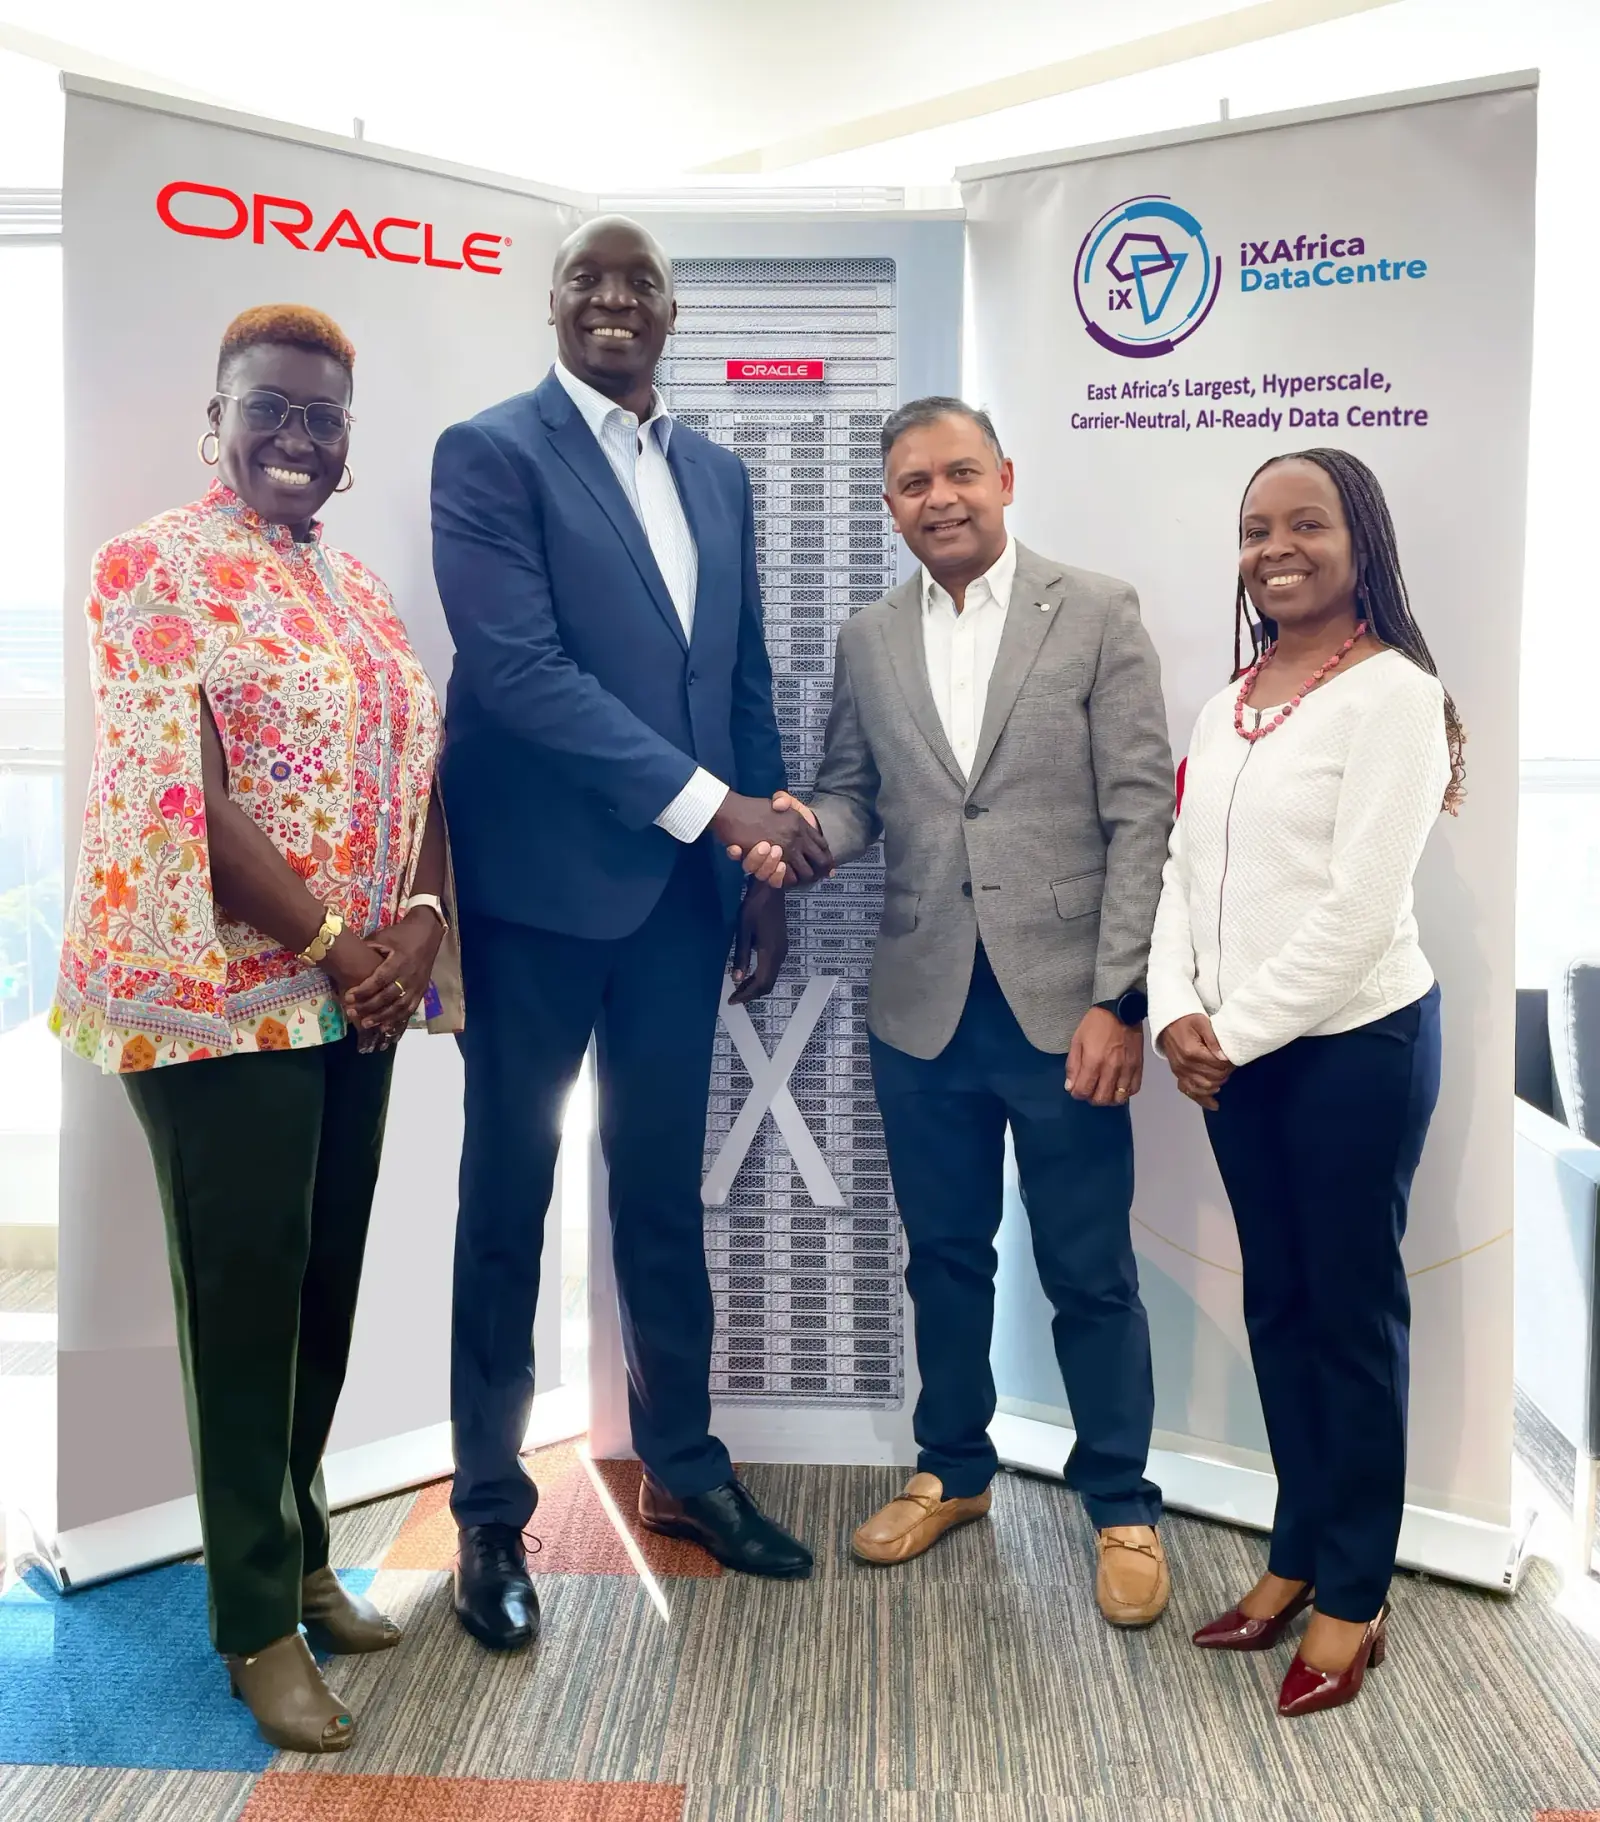
Tatu City: the biggest thing being built right now. Nxtra by Airtel, Airtel Africa's data-centre subsidiary, is developing a two-phase, 44 MW campus inside the Tatu City special planning area on Nairobi's northern edge. Trade press reported the groundbreaking and a US$150 million investment in September 2025 (DataCenterDynamics, 12 Sep 2025), and the PS cites commissioning targeted in 2027.
No completion date is independently confirmed, so our verified directory has tracked it as Under Construction since the groundbreaking, and it now appears on our national infrastructure map too.
Digital Realty NBO2: open. The new Nairobi Two (NBO2) facility in Karen, about 6.5 MW of design load (the PS's essay cites 6.4 MW), expands the former iColo campus and connects more than 100 networks, with access to two internet exchange points. It is real, operating capacity, and it completes iColo's transition to the Digital Realty brand in Kenya.
Microsoft and G42: still a discussion. The geothermal-powered data centre and cloud project announced in May 2024, initially framed at US$1 billion near Naivasha, is described as strategically important but under discussion, with scale, power requirements and commercial structure unresolved. The PS's caution here is deliberate: pursue the investment, but do not place disproportionate guarantees on public institutions. That matches how our directory has treated the project all along.
Konza: the sovereign card. The National Data Centre at Konza Technopolis provides sovereign infrastructure for public services and is positioned as a future site for high-performance computing and sovereign AI. It is the government's own facility, and the essay treats it as a strategic asset rather than a commercial rival.
His own verdict on all of it is refreshingly honest: these projects "do not yet make Kenya a global compute hub. They do make it one of Africa's most credible contenders."
What Kenya has that rivals cannot easily copy
The essay's strongest section is its inventory of national advantages, and it is worth reading as a package rather than a list, because the package is the point.
- Connectivity. Multiple submarine cables land at Mombasa, linking Kenya to Europe, Asia, the Middle East and the rest of Africa, and national fibre pushes that reach across borders. We explain why Kenya is positioned as East Africa's digital hub in a separate guide.
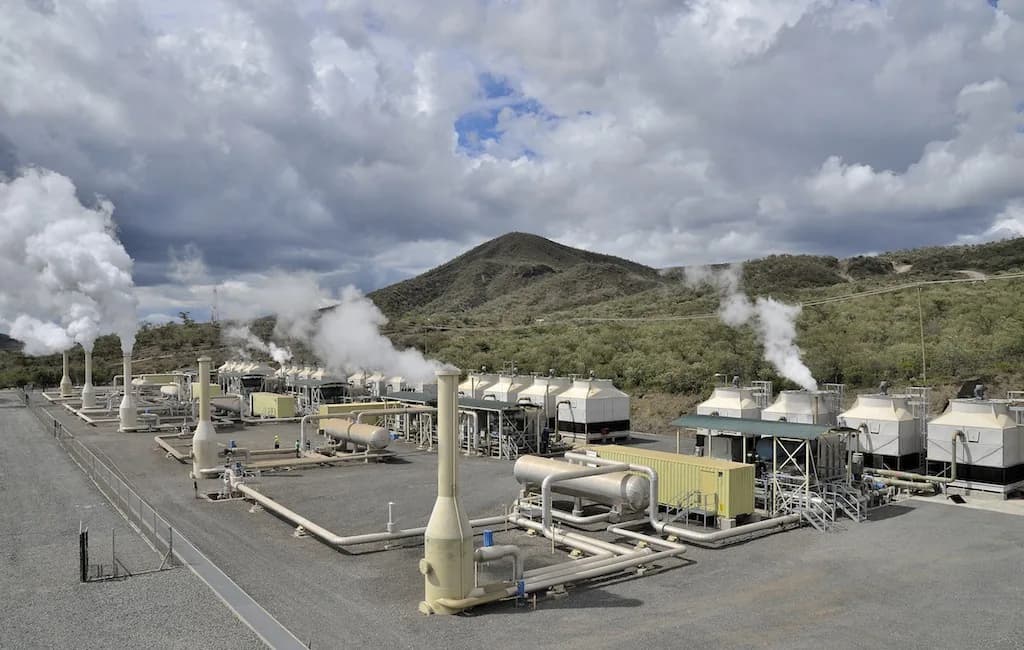
- Geothermal power. Unlike solar or wind, geothermal runs around the clock, and Kenya's best fields (Olkaria near Naivasha, Menengai near Nakuru, and prospects toward Baringo) sit along a corridor that could host dedicated green-compute zones. Our guide to how geothermal energy feeds Kenya's data centres covers the mechanics.
- Local demand. M-PESA, digital banking, eCitizen, e-commerce and a growing tech sector create workloads that can anchor investment. Cloud regions follow customers, not the other way round.
- A policy stack that is moving. The Kenya Cloud Policy, the National AI Strategy 2025 to 2030, the Data Protection Act and the removal of the mandatory 30 percent local shareholding requirement in ICT all push the same direction, and the Communications Authority is reviewing a dedicated data centre licence. We break down the Communications Authority's standalone data centre licence consultation and how tax incentives shape data centre investment in Kenya elsewhere on this site.
- Talent and regional reach. Engineers, developers, financial-services professionals and universities, plus Nairobi's role as a regional headquarters city, which lets facilities here serve markets far beyond Kenya.
On the rules side, one policy thread connects directly to the essay's compute argument: Kenya's data protection framework expects Kenyan personal data to have a Kenyan home, which is the legal pull behind local compute. We unpack Kenya's data sovereignty and localisation rules for anyone building under them.
The warnings he gives his own industry
The essay is unusual for a government piece because it names the failure modes. Ireland shows what happens when data centre growth outruns the grid: 22 percent of national electricity by 2024, and new sites now expected to bring additional renewable generation with them.
Northern Virginia shows the employment trap: thousands of construction jobs, then roughly 50 permanent staff per large facility, which means success must be measured by the digital economy the facilities enable, not headcount inside the halls. Malaysia shows the incentive trap from the other side: it attracted over RM110 billion in approved investment by tying incentives to outcomes, and the PS argues Kenya should reward operating capacity, local cloud services, additional renewable generation and skills, with clawbacks where outcomes are missed.
He also lists the local risks plainly: electricity availability and price, competition with households for infrastructure, noise and land-use friction, cybersecurity and over-dependence on a single cloud provider, and the possibility of building capacity faster than workloads arrive.
For context, Kenya's entire national peak demand is around 2,439MW, which is why every large campus conversation in Kenya is really an energy conversation. The practical discipline he proposes is disclosure: each major project should publish its expected electricity demand, the source of additional generation, water requirements, cooling technology and its contribution to local skills.
His to-do list for the government
The final stretch of the essay is essentially a memo to the state, and it is the part investors will read most closely. Condensed, the asks are:
- A national programme tied to available power, fibre and water, with a published grid-connection queue.
- A transparent large-electricity-load framework, with connection timelines, curtailment rules and clarity on who funds substations and transmission.
- Dedicated geothermal and other renewable capacity for green computing along the Naivasha, Nakuru and Baringo corridor, built as additional megawatts, not reallocated household supply.
- Incentives tied to local value, occupancy and sustainability, with clawbacks when outcomes are missed.
- Aggregated government and regulated-sector cloud demand, with a hard cap on unsustainable guarantees.
- Affordable GPU access for universities, start-ups and public institutions, with clear allocation rules.
- A Nairobi, Konza, Naivasha, Nakuru and Baringo green-compute corridor, including land-use and community-benefit agreements.
- Mombasa positioned as the international cable, edge-computing and disaster-recovery hub, not the default home of the largest AI training campuses.
- Continued engagement with Oracle, Microsoft, Google and others, with a published list of what the state will and will not guarantee.
- A public scoreboard: live megawatts, commissioned cloud regions, occupancy, renewable share, jobs, local procurement and compute hours available to Kenyan innovators.
That last one should sound familiar. A public scoreboard of live megawatts and occupancy is close to describing what this site already does with its directory, and we would happily see the government publish its own version.
Our fact-check verdict
We ran the essay's checkable claims against our own verified data, and it holds up well. The iXAfrica OCI host-partner announcement (27 January 2026) matches our directory entry exactly. The Digital Realty NBO2 opening and its 100-plus networks match our tracked records.
The Nxtra Tatu City figures align with trade-press reporting from September 2025 (groundbreaking, US$150 million) and with our own directory entry, which records the launch target slipping to July 2027; we have now also placed the campus on our national infrastructure map. The cautious framing of Microsoft and G42 matches the line our directory has carried since launch. The Africa capacity gap he cites (about 18 percent of population, under 1 percent of capacity) is consistent with the estimates used across industry research.
What we could not verify: any completion dates. The 2027 commissioning target for Tatu City is a stated plan, not a confirmed date, and the OCI region has no public launch date.
To his credit, the essay itself flags that gap between confidence and capacity. As he puts it, the test is whether "the innovation, computing and intelligence produced by this infrastructure also happen in Kenya." On the evidence in this piece, the government's thinking and the observable pipeline are, for once, pointed in the same direction.
What this means for you
- If you buy infrastructure (CTO, founder, IT lead): the pipeline is real but the live map is still short. Buy against operating capacity today, and negotiate hard against announced capacity tomorrow. Our Nairobi colocation buyer's guide is the practical starting point.
- If you invest or operate: watch the asks, not the speeches. The licence review, the incentive design with clawbacks, and the grid-connection queue are the signals that will decide where capital lands next.
- If you are building a career: the essay's own numbers say construction jobs fade and permanent ones are few, but the enabled digital economy is the prize. The careers that last are in power, networking and the software that runs on top, which our careers and business guides cover from the ground up.
Frequently asked questions
Who is Eng. John Tanui and why does his essay matter?
Eng. John Kipchumba Tanui, CBS, is Kenya's Principal Secretary for ICT and the Digital Economy, the senior civil servant who runs the ministry day to day under the Cabinet Secretary. When he publishes a detailed essay on data centres and computing, it signals what the government is actually thinking: which projects it counts as real, which it treats as talk, and which policy changes it is preparing. The essay was published on LinkedIn on 15 September 2026.
What does "compute" mean in this plan?
Compute is short for computing capacity: the servers, storage and specialised chips that actually process data, housed in data centres. Cables only carry information to and from a country. Compute is where the work happens. The PS's argument is that Kenya spent two decades building the cables (the roads for data) and now needs to build the factories at the end of those roads, so that Kenyan data is processed in Kenya instead of being sent abroad and bought back as services.
Is the Oracle Cloud region live in Kenya yet?
No. President Ruto announced Kenya's first Oracle Cloud Infrastructure (OCI) public cloud region in January 2024. In January 2026, iXAfrica was named as the host partner in Nairobi. As of September 2026 the region is still under development, with no public launch date. When it goes live it will let government agencies, banks and enterprises run cloud services hosted physically in Kenya, with lower latency and clearer data-residency options.
What is being built at Tatu City?
Nxtra by Airtel, the data-centre subsidiary of Airtel Africa, is developing a two-phase, 44 MW data centre campus inside the Tatu City special planning area on Nairobi's northern edge. Trade press reported the groundbreaking and a US$150 million investment in September 2025 (DataCenterDynamics, 12 Sep 2025), and the PS's essay cites commissioning targeted in 2027. Our verified directory lists the project as Under Construction, since no completion date is independently confirmed yet.
What did the PS say about the Microsoft and G42 project?
He was notably careful. The project, announced in May 2024 as a roughly US$1 billion geothermal-powered data centre and cloud venture near Naivasha, is described as strategically important but still under discussion, with its scale, power requirements and commercial structure unresolved. That matches how our directory treats it: an ambition, not committed capacity. His advice was to keep pursuing the investment without placing unsustainable guarantees on public institutions.
Why does Ireland keep coming up in Kenya's data centre debate?
Ireland is the cautionary tale of what success looks like when it outruns planning. Data centres there grew from 5 percent of the country's metered electricity in 2015 to 22 percent in 2024, and new sites are now expected to bring their own additional generation. The PS uses Ireland, and Northern Virginia's construction-heavy-then-operations-light job pattern, to argue that Kenya should design its rules before the pressure arrives, not after.