Kenya's data centre market is entering its most significant growth phase since the first commercial facilities were built in Nairobi a decade ago. With an estimated market value of $180–220 million in 2025 and projections pointing toward $400–500 million by 2030, the country is positioning itself as the digital infrastructure capital of East Africa. This is not speculation, it is a trend backed by concrete capacity expansions, new market entrants, and structural demand drivers that are unlikely to reverse.
Understanding this market requires looking beyond the headline numbers. The value of a data centre market is not just in the physical facilities themselves, but in the ecosystem of connectivity, power, skilled labour, regulatory frameworks, and demand sources that determine whether those facilities are economically viable. Kenya has strengths in several of these areas and weaknesses in others, and the next five years will determine how quickly the gaps close.
Current State of the Market in 2025
Kenya currently has approximately 10 operational data centre facilities, concentrated heavily in Nairobi and its immediate environs. The total IT power capacity across these facilities is estimated at 15 megawatts, with the majority housed in three large colocation providers: iXAfrica, Africa Data Centres, and Safaricom. A handful of smaller operator-built and enterprise facilities account for the remainder.
The market can be segmented into three tiers. The first tier consists of carrier-neutral colocation providers, iXAfrica's NBOX1 and NBOX1.1 facilities in Mombasa Road, and Africa Data Centres' facilities in Sameer Park and Westlands. These offer retail and wholesale colocation, interconnection to multiple networks, and are the facilities that attract international cloud providers, content delivery networks, and enterprises. The second tier includes telecom-integrated facilities, primarily Safaricom's data centres that support its mobile network, M-Pesa processing, and enterprise cloud services. The third tier comprises smaller, often single-tenant facilities built by banks, government agencies, and technology companies for their own use.
Revenue in the Kenyan data centre market comes from several streams. Colocation space rental (where customers pay per rack, per kilowatt, or per square metre) is the largest single segment. Interconnection revenue, earned when carriers, cloud providers, and enterprises connect to each other within a facility, is growing faster than colocation itself. Managed services, where the facility operator also manages the customer's servers, storage, and network, commands premium pricing but remains a smaller portion of the market. ancillary services like backup power, cooling, and remote hands round out the revenue mix.
Kenya's colocation pricing is competitive by African standards. A full rack in a Tier III Nairobi facility typically costs between KES 60,000 and KES 120,000 per month, depending on power density, location, and contract length. This compares favourably with South Africa, where equivalent space in Johannesburg ranges from KES 80,000 to KES 150,000, and is significantly cheaper than Lagos, where power costs and generator fuel push rack rates above KES 150,000.
The Key Demand Drivers
Several structural forces are driving data centre demand in Kenya, and understanding these is essential for any investment analysis. The first and most significant is enterprise cloud migration. Kenyan banks, telcos, insurance companies, and government agencies are moving workloads from on-premises server rooms to cloud environments, either public clouds (AWS, Azure, Google Cloud) or private clouds hosted in colocation facilities. This transition is still in its early stages. Industry estimates suggest that only 20–30% of Kenyan enterprise workloads have moved to the cloud, compared to 60–70% in mature markets. The remaining migration represents years of demand growth.
The second driver is artificial intelligence and machine learning. AI workloads require GPU-dense computing environments that are fundamentally different from traditional server infrastructure. GPU servers consume 4–10 times more power than standard servers and generate correspondingly more heat. This is creating demand for high-density colocation, facilities that can deliver 20–40 kW per rack instead of the traditional 5–10 kW. Kenya's first dedicated GPU-capable facilities are being planned, and the demand from AI startups, research institutions, and international companies running inference for African markets is substantial.
The third driver is government digitalisation. Kenya's e-Citizen platform, which now hosts over 5,000 government services, requires domestic data processing. The government's data sovereignty requirements, codified in the 2019 Data Protection Act, mean that certain categories of government and citizen data must be processed within Kenya's borders. This creates a floor of demand that is independent of private sector cycles. The Huduma Namba biometric registration programme, digital tax systems (iTax, TIMS), and the ongoing computerisation of land records, court systems, and health records all contribute to growing government demand for data centre capacity.
The fourth driver is financial services modernisation. Kenya's banking sector is one of the most sophisticated in Africa, and the reliance on digital channels (mobile banking, USSD, agent banking) means that every transaction, every account query, every loan application generates data processing demand. The National Payment System alone processes billions of shillings daily, and the backend infrastructure supporting M-Pesa, Airtel Money, and bank-to-bank transfers requires robust, always-on data centre facilities.
Investment and Expansion Plans
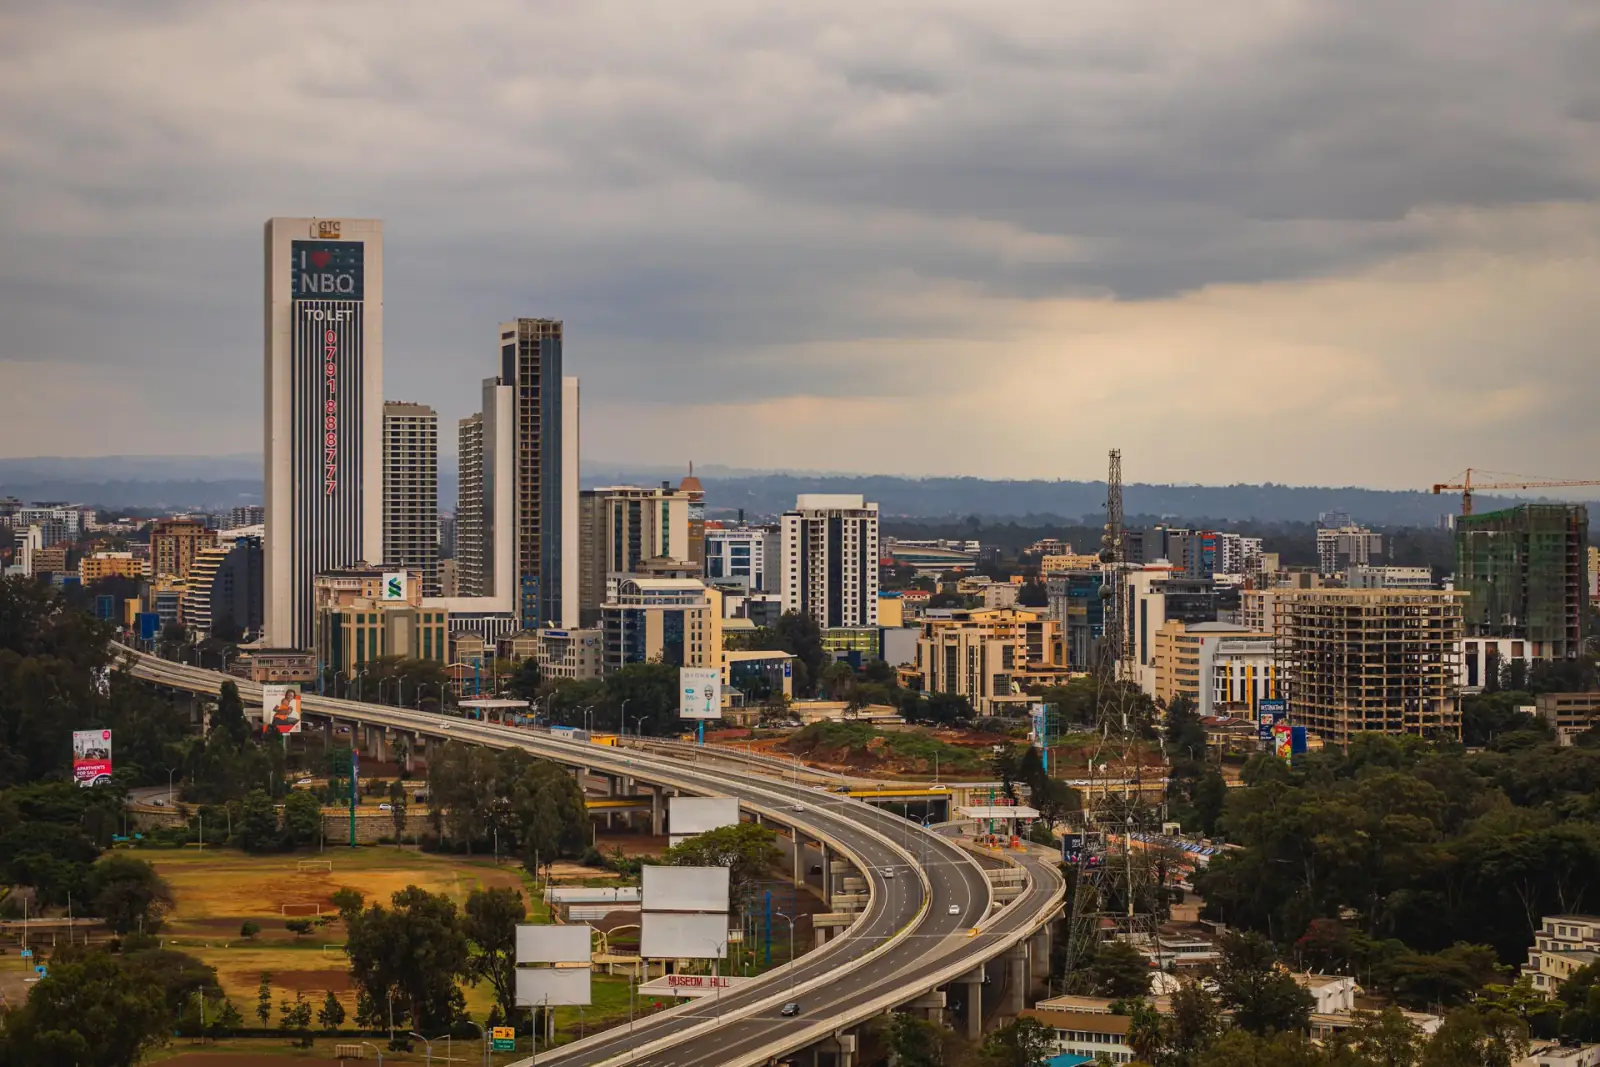
The most visible investment in Kenya's data centre market is iXAfrica's NBOX1.1 expansion. iXAfrica, backed by African infrastructure investment funds, opened its first facility (NBOX1) in 2023 with an initial IT load capacity of 2.5 megawatts. NBOX1.1, currently under construction on the same campus along Mombasa Road, will add a further 4.5 megawatts, making the combined campus the largest single data centre site in East Africa at 7 megawatts. The facility is designed to Tier III standards with N+1 redundancy on power and cooling, and will include dedicated GPU-ready zones for AI workloads.
Africa Data Centres, a subsidiary of Liquid Intelligent Technologies (now part of the Cassava Technologies group), operates multiple facilities in Nairobi. Their Sameer Business Park facility and their Westlands site together provide several megawatts of IT capacity. The company has publicly stated ambitions to expand its East African footprint, with Kenya as the anchor market. Their advantage is the integration with Liquid's fibre network, which spans over 100,000 kilometres across the continent and provides a built-in customer base of connectivity clients who also need data centre services.
Safaricom, Kenya's largest telecom operator by revenue and subscriber base, operates data centres that primarily serve its own needs, mobile network switching, M-Pesa transaction processing, and its Cloud and Hosting business unit. Safaricom has been expanding its enterprise cloud offerings, competing directly with international providers by offering local data residency, lower latency, and bundles that combine connectivity, cloud, and security. While Safaricom's facilities are not carrier-neutral colocation in the traditional sense, the company is a significant source of data centre demand in its own right and a potential wholesale partner.
Beyond the established players, several new entrants are evaluating the Kenyan market. Kenya Data Centres, a local company, has announced plans for a facility targeting SME colocation customers. Global TLS, a smaller operator, runs a facility in Nairobi focused on the mid-market. The entry of a hyperscale provider (AWS, Microsoft Azure, or Google Cloud building a direct presence rather than partnering through a colocation provider) would be a transformative event for the market, though none has publicly committed to a Nairobi facility as of 2025.
Kenya vs. Competitor Markets
Understanding Kenya's position requires comparing it against Africa's other major data centre markets. South Africa dominates the continent with over 200 megawatts of IT load capacity across dozens of facilities in Johannesburg, Cape Town, and Durban. South Africa's advantage is a large domestic enterprise market, mature financial services sector, and proximity to the rest of Southern Africa. However, South Africa faces power grid challenges (load shedding has been a persistent issue) and higher energy costs compared to Kenya's renewable-heavy grid.
Nigeria's market is centred on Lagos, with an estimated 15–20 megawatts of capacity. Nigeria's enormous population (220 million) and large economy create substantial demand, but infrastructure challenges (unreliable power, right-of-way issues for fibre, and regulatory uncertainty) have constrained growth. Nigeria is a high-potential, high-difficulty market.
Egypt's market, concentrated in Cairo and the new administrative capital, has grown rapidly with investments from Gulf-based operators. Egypt's advantage is access to European and Asian markets via submarine cables, but its market is more domestically focused and less integrated into the broader African internet ecosystem than Kenya's.
Kenya's competitive advantages are specific and structural. The country has four submarine cable landing stations in Mombasa (more than any other East African country) providing direct connectivity to Europe, Asia, the Middle East, and Southern Africa. Kenya Power's grid, while not without reliability issues in some areas, draws over 90% from renewable sources (geothermal, hydro, wind, solar), giving Kenya some of the lowest carbon-intensity electricity in the world and a structural cost advantage as global companies face pressure to reduce their carbon footprint. Kenya's strategic location (within 100 milliseconds of latency for the entire East African Community of 300 million people) makes it the natural hub for regional digital services.
Market Projections 2025–2030
Based on current expansion plans, demand trends, and the structural drivers outlined above, Kenya's data centre market is projected to grow at a compound annual rate of 15–20% between 2025 and 2030. Total IT power capacity is expected to increase from approximately 15 megawatts to 25–30 megawatts, driven primarily by iXAfrica's expansion, Africa Data Centres' growth, and new entrants.
Colocation revenue is expected to grow from approximately $100 million to $220–250 million, while managed services and interconnection revenue will grow faster, roughly doubling from $60–80 million to $150–200 million. The total addressable market, including the value of services consumed within data centres (cloud computing, content delivery, financial transaction processing), is substantially larger, potentially $1–2 billion by 2030.
The investment required to support this growth is estimated at $300–500 million over the five-year period. This includes new facility construction, expansion of existing sites, power infrastructure upgrades, and the development of specialised capabilities like GPU-ready zones and liquid cooling systems. The returns on this investment are attractive by African infrastructure standards, colocation facilities in Nairobi typically achieve 12–18% unlevered IRR, with higher returns available for operators who can differentiate on services, connectivity, or energy efficiency.
The Kenyan government has now put its own weight behind this trajectory. Writing in September 2026, the Principal Secretary for ICT and the Digital Economy, Eng. John Kipchumba Tanui, framed the global context (a colocation and interconnection market worth about US$119 billion in 2025, heading toward roughly US$147 billion in 2026) against Africa's share of it (under 1 percent of global data centre capacity, for a continent holding about 18 percent of the world's population). His essay, which we fact-checked and unpacked in Kenya's data centre and compute hub plan, explained, commits the state to converting that gap into operating capacity, which is exactly the demand side this projection assumes.
Risks and Challenges
No investment analysis is complete without an honest assessment of risks. Kenya's data centre market faces several. Power reliability remains a concern, while Nairobi's central business districts and industrial areas have relatively stable supply, the grid's overall reliability has degraded in some peri-urban areas, forcing data centres to rely heavily on diesel generators during outages. This increases operating costs and carbon emissions, partially negating the advantage of Kenya's renewable generation mix.
Currency risk is significant. Colocation contracts are typically denominated in Kenya Shillings, but equipment, generator fuel, and many construction materials are priced in US dollars. The KES has depreciated from approximately 100 per USD in 2020 to over 150 per USD in 2025, creating a cost-revenue mismatch that operators must manage through hedging, contractual escalation clauses, or USD-denominated pricing for international clients.
The regulatory environment, while improving after the Communications Authority's decision to bring data centres under the licensing framework, still has uncertainties. The KES 15 million NFP-T2 licence fee is manageable for established operators but may be a barrier for new entrants or smaller facilities. Tax policy, including VAT treatment of data centre services and import duties on equipment, also affects competitiveness.
Finally, the skills gap is a real constraint. Kenya produces many software engineers and IT graduates, but the specialised skills required to design, build, and operate data centres (power engineering, cooling system management, structured cabling, facility management) are in short supply. Operators are investing in training programmes, but scaling these to support a 2x growth in capacity over five years is a non-trivial challenge.
The Opportunity
Despite these risks, the investment case for Kenyan data centres is compelling. The market is growing from a small base, demand drivers are structural and multi-year, and the competitive landscape is less crowded than in South Africa or Nigeria. Kenya's renewable energy advantage will become increasingly valuable as global companies face stricter environmental reporting requirements and carbon reduction targets. The country's connectivity advantage (four submarine cables, a well-functioning internet exchange point, and a growing fibre network) makes it the natural digital hub for a region of 300 million people.
For investors, the opportunity is not just in building facilities, but in the entire value chain: connectivity, managed services, edge computing, and the emerging GPU infrastructure needed for AI workloads. The next five years will determine whether Kenya cements its position as East Africa's data centre capital, or cedes ground to faster-moving competitors. All current indicators point toward growth.