Amazon Web Services has committed a further $1.5 billion to African infrastructure through 2029, on top of more than $819 million invested since 2018, and says it has trained over one million Africans in cloud and AI skills. Jyoti Ball, AWS's general manager for sub-Saharan Africa, delivered the numbers at the AWS Summit in Johannesburg, and iAfrica.com's report on 12 September 2026 did something trade coverage rarely does: it printed the commitment and stress-tested the argument behind it in the same article.
That argument deserves the attention of anyone tracking African data centre capacity, because it is the same argument Kenyan policymakers use. This article walks through what AWS committed, why the leapfrog analogy that frames these commitments is appealing and incomplete, and what the numbers imply for a market like Kenya.
What AWS Actually Committed
The headline is the $1.5 billion through 2029. The useful details sit around it. The Cape Town cloud region now carries 154 services, which Ball used to argue that African developers are no longer working with a stripped-down regional feature set. Her framing of strategy was about direction of trade: enabling local developers to build for regional markets rather than consuming technology developed elsewhere.
The comparison set is Microsoft, not Google or Oracle (for now). Microsoft has spent R20.5 billion on data centres in Johannesburg, Cape Town and Durban, with a further R5.5 billion Centurion facility planned, roughly $1.4 billion combined at current rates, per the iAfrica report. Two hyperscalers at $1.4 to $1.5 billion each is a real pattern, and it sets the scale at which serious African cloud infrastructure is being financed: billions, spread over years, concentrated in South Africa first.
The Leapfrog Case, and Its Gap
Ball's central case is the one African ICT ministers have made for two decades: the current AI cycle offers Africa another chance to bypass stages that wealthier economies passed through. Her precedent is mobile money: "Africa did not wait for conventional banking infrastructure to become widespread before developing large-scale mobile payment systems," pointing to South Africa's jump from limited mobile connectivity in the early 1990s to more than 100 million connections.
iAfrica's critique of that analogy is the best part of the report, and it is analytically correct. Mobile money leapfrogged branch banking because the infrastructure it actually depended on (mobile networks) was already built. Africa did not skip telecoms; it skipped bank branches by running services over telecoms. AI's equivalent dependency is compute, and that has not been built. The report's numbers make the point stark: Africa holds roughly 1% of the world's data centres against about 15% of global population, and McKinsey projects that African capacity must rise from around 0.4 gigawatts to as much as 2.2 gigawatts by 2030, requiring $10 billion to $20 billion of investment.
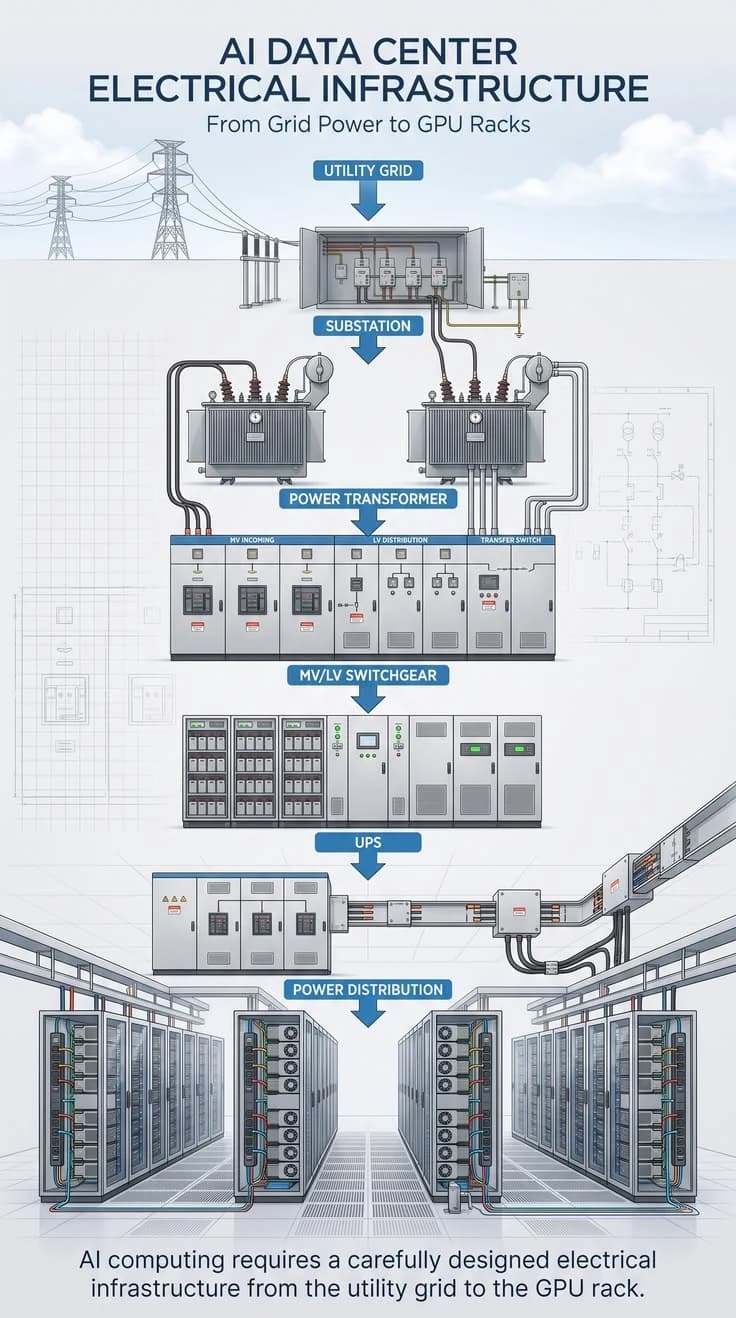
Read those two numbers against the commitments and the gap quantifies itself. AWS's $1.5 billion and Microsoft's $1.4 billion equivalent together cover a fraction of the McKinsey range. The leapfrog story is therefore not wrong; it is a description of where the demand is heading, funded so far at a tenth of the level its own analogy requires. Leapfrogs do not skip infrastructure. They skip incumbent business models by building the infrastructure early. That is what M-Pesa rode, and it is what any African AI story must eventually stand on: powered halls with racks in them.
Why the Cloud Region Detail Matters for East Africa
There is a geographic asymmetry inside the numbers that matters for Kenya. The region Ball cites is Cape Town; the $1.4 billion Microsoft figure is South African. Southern Africa is where hyperscaler capital has concentrated, because it has the grid, the fibre and the enterprise base today. East Africa's share of that investment wave is so far measured in partnerships and positioning rather than regions: Kenya's pitch leans on iXAfrica's hyperscale AI-ready campus, Digital Realty's freshly launched NBO2, and a power story (geothermal-backed, low-carbon, competitively priced) that is genuinely differentiated on the input costs that matter for compute.
The implication is not that Kenya loses the wave. It is that Kenya wins it by making the leapfrog's dependency investable: grid capacity into industrial areas, a licensing regime that treats data centres as infrastructure (the Communications Authority's standalone licence consultation is live), and a directory-grade evidence base that lets financiers verify what exists. Hyperscalers build regions where demand, power and permitting line up; Kenya's job is the lining up.
How to Track Commitments Like These
The verification habit this site applies to every hyperscaler announcement applies here. Commitments are dated intentions; capacity is commissioned MW. The numbers to watch from this announcement are none of the headline figures: they are the eventual facility list (which halls, which countries), the MW those halls draw, and the service count trajectory of any East African region if one is announced. Against the McKinsey 2.2 GW target for 2030, four years is short, and power projects move at the speed of transmission lines. That arithmetic, not enthusiasm, is what will decide whether 2029 reads as the start of Africa's compute decade or the preamble to it.
Sources: iAfrica.com, "AWS Commits $1.5bn to Africa Through 2029 and Makes the Leapfrog Case. The Analogy Has a Gap" (12 September 2026), reporting remarks by Jyoti Ball (AWS general manager, sub-Saharan Africa) at the AWS Summit in Johannesburg; AWS investment and training figures, Cape Town service count, Microsoft R20.5 billion / R5.5 billion spend, and McKinsey 0.4 to 2.2 GW / $10-20 billion projections as reported therein. Kenya facility figures from the DC254 directory (September 2026 verification).